State-level Cryptocurrency Laws: New York, We Love You, But You’re Bringing Cryptocurrency Down — Part #2
This is the second post of a three-part series on discrepancies in the US between state and federal laws on cryptocurrency. By Philip C. Berg
The first post, State vs. Federal Laws in Cryptocurrency: Blue Sky, or Running in the Red? ran on BX3 Capital’s blog.
In 2016 the Office of the Comptroller of the Currency(OCC), which issues all national bank charters, initially proposed the concept of granting special-purpose national bank charters to financial technology (fintech) companies that offer banking services such as lending, but do not take deposits. After a two-year period of comment and rulemaking, on July 31 the OCC disclosed that it would begin accepting applications for such fintech charters. Comptroller Joseph Otting said in the public announcement, “Providing a path for fintech companies to become national banks can make the federal banking system stronger by promoting economic growth and opportunity, modernization and innovation, and competition.” This reignited the New York Department of Financial Services’ (NYDFS) legal dispute with the OCC, seeking to block these fintech charters. In its lawsuit, the NYDFS claims that regulatory authority over such limited-purpose finance companies should remain at the state level, as it currently is for companies such as money transmitters, insurance agents and bail bondsmen. Under the NYDFS’ view, all fintech/blockchain exchanges and cryptocurrency lenders operating in New York or having New York-resident customers should be required to register under New York’s sweeping BitLicense regime, with no federal alternative. BitLicense applications typically take years to be approved — or rejected — and require considerable paperwork and legal counsel in the process. This has led many in the fintech/blockchain sector to exclude New York residents from investing or transacting with them.
Contrary to the NYDFS’ view, the existence of dual competing regulatory regimes for fintech financial companies — similar to our dual federal and state banking system — is optimal to foster competition, development and investment. Under such a regime a crypto-lender, crypto-exchange or crypto-custodian could decide whether to be federally chartered — and thus subject to OCC supervision and regulation on par with full-service national banks — or to be state regulated, such as under New York’s BitLicense framework. The advantages of this competing dual system have already become manifest: at nearly the same time that the NYDFS re-filed its lawsuit against the OCC in September, the NYDFS granted Gemini Trust, the cryptocurrency exchange founded by the Winklevoss twins, permission to issue its Gemini Dollar cryptocurrency. Gemini had sought SEC permission to issue federally regulated crypto-securities multiple times, and was rejected each time. Clearly the NYDFS knew that if it was going to credibly argue that crypto-banking should be regulated solely by the states, it would have to show that state regulators were currently approving such licenses and charters, and not merely sitting on them.
In the suit, the NYDFS’ primary argument against the OCC’s power to grant fintech bank charters is that the OCC is exceeding its authority given by Congress under the National Banking Act of 1863(NBA). Although the OCC likely has the better argument as to the extent of its bank-chartering authority under the NBA, in prior such disputes over special-purpose national bank charters (such as for credit card banks and trust companies), Congress subsequently expressly granted the OCC such authority. Instead of leaving the current NYDFS vs OCC dispute to the courts, Congress could expressly authorize the OCC to grant special-purpose bank charters to non deposit-taking fintech companies, thus making the lawsuit moot.
And in connection with such authorization, Congress could take the further step of federal preemption, i.e., providing that to the extent such charters are granted, it is the express intent of Congress that state laws regarding the organization, registration, examination and operation of such OCC-chartered entities are preempted by federal law (as they are with other federally chartered banks). This would give fintech finance companies an alternative regulatory regime without any interstate inconsistency and without legal uncertainty while the NYDFS’ lawsuit is litigated. These nationally chartered fintech companies, like other national banks, would be answerable only to the applicable federal banking regulators, and not subject to more than 50 other varied regulations. In today’s borderless marketplaces, such a national alternative should be available to ensure our country’s continued leadership in this critical area of innovation.
I say, bring on the dual federal and state cryptocurrency banking system.
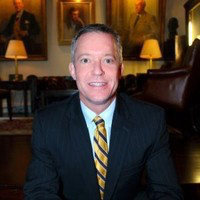
Philip C. Berg, a longstanding lawyer with Otterbourg P.C.and chairman of its corporate department with deep expertise in the cryptocurrency sector, has an array of thoughts on how regulation of virtual currency and blockchain assets should play out in the medium to long-term on both the state and federal level. Whether about how federal policy would harmonize state-level regulations or how light-touch regulation would let US investment flourish, across a series of op-ed articles, Berg offers his insights on what tack the Securities and Exchange Commission (SEC) may want to consider as digital assets become an indelible facet of the investment landscape, as well as how the new Congress may wish to proceed on the legislative front in 2019.
Berg is serving as a legal adviser to Rep. Warren Davidson, the Ohio Congressman who spearheaded a Congressional roundtable on cryptocurrency in September and is in the process of drafting bills intended to bring regulatory clarity to the burgeoning blockchain industry.
Published December 14, 2018. Views are the author’s own and are not financial, legal or tax advice.